

9 Crown Row, Bracknell, Berkshire, RG12 0TH
9 Crown Row, Bracknell, Berkshire, RG12 0TH
62 High Street, Sunninghill, Ascot, Berkshire, SL5 9NN
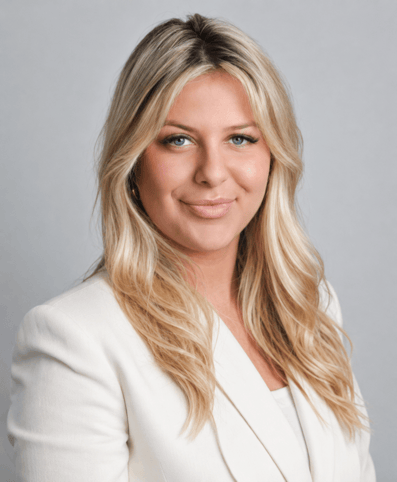
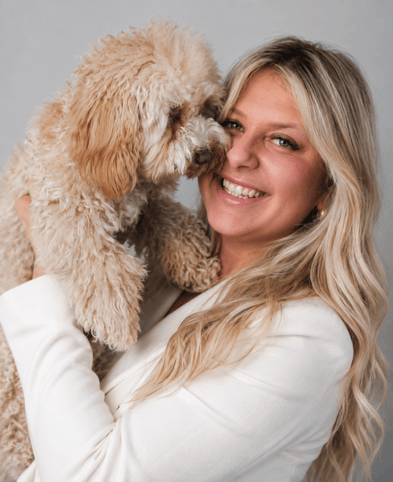
Sales Valuer
Freya started her career in estate agency at the age of 18. Founding her love of property through her Dad who was a developer, she has gained many years experience selling and valuing properties across Berkshire, but having been born in Heatherwood Hospital, she has Ascot in her veins! Friendly and personable, Freya is passionate about helping clients and enjoys building new relationships. Away from work, she loves travelling with the family, pub gardens, shopping, and most importantly spending time with her dog, Dolly the Maltipoo!
One of my funniest memories is…
Swimming with pigs in the Bahamas.
You might be surpsied to know that…
Elton John has been my neighbour.
On Sunday mornings, you can usually find me…
Walking the dog around Ascot racecourse.
My guilty pleasures are…
Prosecco, Prosecco, Prosecco!
The thing I like best about my job is…
The people.
The best piece of advice I’ve been given is…
You come into this world with no money, and you go out this world with no money.
21 Feb 2017
Something like 25% of a council’s revenue is raised through council tax with government grants and income from other sources such as business rates making up the remainder.
The tax pays towards local services and also towards certain precepted authorities (such as the local parish council). In the past, council tax took the form of domestic rates and the amount payable was calculated on the basis of a property’s notional rental value at a specific date. Properties were divided into bands with certain bands paying a ratio of the total tax levied annually.
In the 1980s, the government introduced a replacement tax system based on the individual, the logic being that everyone in a community should pay an equal share of the cost of their public services. However, the tax was very unpopular with some elements of society and was eventually abandoned for council tax, which strongly resembles domestic rates in that it is based on council tax bands, divided based upon a notional capital value as at 1991.
In England, each dwelling is allocated to one of eight bands (Band A to Band H) with new properties being assigned a nominal 1991 value for this purpose.
Each local authority sets a tax rate based on its annual budget. That levy is expressed with reference to Band D properties on the assumption that they are inhabited by two liable adults (i.e. there is no deduction due for single occupancy).
The nominal Band D property total is calculated by adding together the number of properties in each band and multiplying by the band ratio. So 100 Band D properties will count as 100 nominal Band D properties, whereas 100 Band C properties will count as 89 nominal Band D properties.
Each local authority adds together the Band D amounts for their area (or subdivisions of their area in the case of civil parish council precepts) to reach a total Band D council tax bill.
To calculate the council tax for a particular property a ratio is then applied. For example, a Band D property will pay the full amount, whereas a Band H property will pay twice that amount. There is no upper limit for band H. This means that in reality, someone who lives in a multi-million home, will pay 3 times more than someone in a bedsit which falls into Band A.
The counter argument is that the local services consumed by the occupant of a mansion are likely to be no greater than the services consumed by the occupant of a bedsit.
Properties in England are put into one of eight bands (A-H), depending on the price they would have sold for in April 1991:
| Council tax band | Ranges of value |
| A | Up to £40,000 |
| B | More than £40,000 and up to £52,000 |
| C | More than £52,000 and up to £68,000 |
| D | More than £68,000 and up to £88,000 |
| E | More than £88,000 and up to £120,000 |
| F | More than £120,000 and up to £160,000 |
| G | More than £160,000 and up to £320,000 |
| H | More than £320,000 |



 General news
 General news
 General news