

9 Crown Row, Bracknell, Berkshire, RG12 0TH
9 Crown Row, Bracknell, Berkshire, RG12 0TH
62 High Street, Sunninghill, Ascot, Berkshire, SL5 9NN
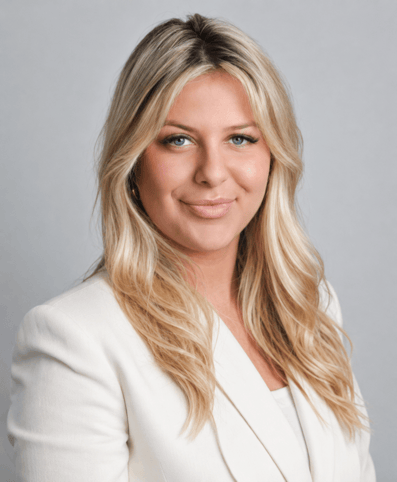
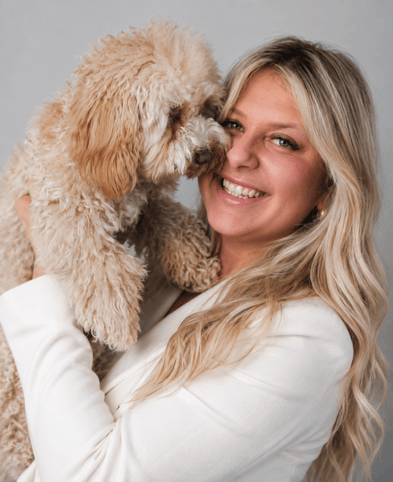
Sales Valuer
Freya started her career in estate agency at the age of 18. Founding her love of property through her Dad who was a developer, she has gained many years experience selling and valuing properties across Berkshire, but having been born in Heatherwood Hospital, she has Ascot in her veins! Friendly and personable, Freya is passionate about helping clients and enjoys building new relationships. Away from work, she loves travelling with the family, pub gardens, shopping, and most importantly spending time with her dog, Dolly the Maltipoo!
One of my funniest memories is…
Swimming with pigs in the Bahamas.
You might be surpsied to know that…
Elton John has been my neighbour.
On Sunday mornings, you can usually find me…
Walking the dog around Ascot racecourse.
My guilty pleasures are…
Prosecco, Prosecco, Prosecco!
The thing I like best about my job is…
The people.
The best piece of advice I’ve been given is…
You come into this world with no money, and you go out this world with no money.
13 Mar 2018
The 2nd of November 2017 marked a significant turning point for first-time buyers in England and Wales, as the UK government introduced substantial savings on Stamp Duty Land Tax (SDLT). For those looking to get onto the property ladder, this new policy could provide much-needed financial relief, especially for those with limited funds for purchasing a home. The new stamp duty exemption applies to first-time buyers purchasing properties up to £500,000, with homes priced at £300,000 or below being entirely free of SDLT. For properties priced above £300,000, SDLT charges will only apply to the portion of the property price that exceeds that threshold.
This change in policy provides a significant boost to first-time buyers, as the table below illustrates:
| Purchase Price (£) | Old SDLT (£) | New SDLT for First-Time Buyers (£) | Saving for First-Time Buyers (£) |
|---|---|---|---|
|
£150,000 |
£500 |
None |
£500 |
|
£200,000 |
£1,500 |
None |
£1,500 |
|
£250,000 |
£2,500 |
None |
£2,500 |
|
£300,000 |
£5,000 |
None |
£5,000 |
|
£350,000 |
£7,500 |
£2,500 |
£5,000 |
|
£400,000 |
£10,000 |
£5,000 |
£5,000 |
|
£500,000 |
£15,000 |
£10,000 |
£5,000 |
While the stamp duty waiver offers great savings, there are certain conditions that first-time buyers must meet to qualify for the relief. These conditions are as follows:
These eligibility criteria apply not just to properties in the UK but also to any property owned anywhere in the world. If you or your co-purchaser have previously owned property abroad, you would still be excluded from claiming first-time buyer SDLT relief.
For first-time buyers purchasing through formal shared ownership schemes, the SDLT relief also offers significant savings. When buying through these schemes, buyers only pay SDLT on the portion of the home that they are purchasing. This can make the purchase of a shared ownership home even more affordable, especially for those who are looking to get onto the property ladder without buying a home outright.
However, it’s important to note that this exemption does not apply to informal shared ownership arrangements, such as when you buy a property jointly with a family member or friend outside of a formal scheme. Only formal shared ownership homes offered by registered providers are eligible for SDLT relief under this scheme.
The SDLT exemption for first-time buyers is undeniably good news for those looking to buy their first home, as it offers substantial savings. By removing or reducing SDLT, buyers can now allocate more of their budget towards a deposit or other upfront costs, which can make the dream of homeownership more achievable. For example, a first-time buyer purchasing a home priced at £300,000 would save £5,000 in SDLT under the new rules, which could instead be used towards furnishing their new home or other essential expenses.
However, there is also the possibility that these savings could drive up property prices in certain areas. With more first-time buyers being able to afford homes in the £300,000 to £500,000 range, competition for properties in this price bracket could intensify. In an open market, this increased demand could lead to higher prices, especially for properties valued just under the £500,000 threshold.
This could also be seen as good news for existing homeowners who are selling properties in this price range. With more buyers vying for homes that fall under the £500,000 limit, sellers could potentially achieve higher sale prices. As a result, the SDLT exemption could inadvertently benefit homeowners as much as it helps first-time buyers.
In addition to the immediate financial savings, the SDLT relief could also have long-term benefits for the housing market. By making homeownership more accessible to first-time buyers, the exemption helps to stimulate demand at the lower end of the market. This, in turn, could encourage the construction of more affordable homes, as developers seek to meet the increased demand from first-time buyers.
Moreover, by reducing the upfront costs of buying a home, the SDLT waiver could help to improve long-term financial stability for first-time buyers. With less money spent on SDLT, buyers can put more of their savings towards building equity in their home, which can help to provide financial security in the years to come.
The SDLT exemption introduced in November 2017 represents a major opportunity for first-time buyers in England and Wales. By removing SDLT for properties priced up to £300,000 and reducing it for properties up to £500,000, the government has significantly reduced the upfront costs of buying a home. This change in policy offers significant savings for first-time buyers, potentially making homeownership more achievable for many.
However, while the SDLT relief provides a financial boost to buyers, it could also drive up competition for properties in the £300,000 to £500,000 range. As a result, existing homeowners could benefit from higher property prices in this segment of the market.
For first-time buyers looking to take advantage of the SDLT exemption, it’s important to act quickly and make the most of this opportunity before house prices potentially rise. Whether you’re buying a home outright or through a shared ownership scheme, the SDLT relief can help to make your first home purchase more affordable and financially secure.
Related article:



 Buyers
 Buyers
 Buyers