

9 Crown Row, Bracknell, Berkshire, RG12 0TH
9 Crown Row, Bracknell, Berkshire, RG12 0TH
62 High Street, Sunninghill, Ascot, Berkshire, SL5 9NN
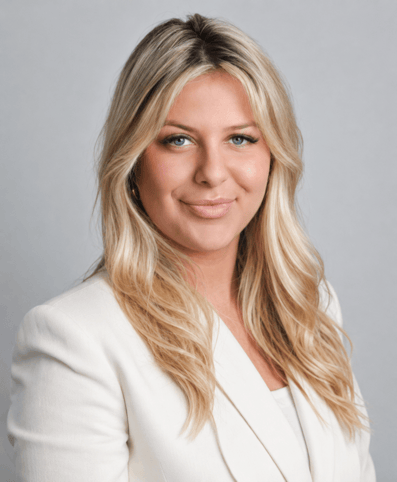
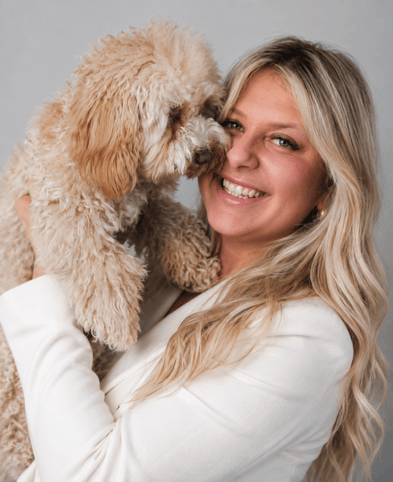
Sales Valuer
Freya started her career in estate agency at the age of 18. Founding her love of property through her Dad who was a developer, she has gained many years experience selling and valuing properties across Berkshire, but having been born in Heatherwood Hospital, she has Ascot in her veins! Friendly and personable, Freya is passionate about helping clients and enjoys building new relationships. Away from work, she loves travelling with the family, pub gardens, shopping, and most importantly spending time with her dog, Dolly the Maltipoo!
One of my funniest memories is…
Swimming with pigs in the Bahamas.
You might be surpsied to know that…
Elton John has been my neighbour.
On Sunday mornings, you can usually find me…
Walking the dog around Ascot racecourse.
My guilty pleasures are…
Prosecco, Prosecco, Prosecco!
The thing I like best about my job is…
The people.
The best piece of advice I’ve been given is…
You come into this world with no money, and you go out this world with no money.
26 Mar 2019
Prior to the World Financial Crisis in 2008 most lenders’ criteria were based on a few simple criteria. These included Loan to Value, Salary Multiplier, the borrower’s credit history and the type and condition of the property.
In the aftermath of the credit crunch the UK Government intervened and set out criteria that needed to be applied by lenders when considering loan applications. The idea was that ‘affordability’ was an important factor, both at the time of the loan and later on, if circumstances were to change.
Mortgage affordability tests (otherwise known as stress tests) are now a legal requirement when considering lending for property.
A mortgage company will now have to consider a borrower’s expenditure as well as their income. They will also consider notional increases in the lending rate and calculate what impact this is likely to have on a borrower’s ability to continue making their monthly mortgage payments. This additional level of paperwork might seem frustrating but the reason for the criteria is to help better ensure that borrowers are not overextending themselves.
To do this the lender will ask detailed questions about the lender’s income, employment status, age, personal circumstances, other debts and liabilities and lifestyle. The answers provided by the lender will need to be supported by evidence too, such as payslips, P60s, bank statements, etc.
The maximum amount you are likely to be able to borrow and the cost of borrowing (the interest rate and other associated charges) is linked to a combination of;
Mortgage affordability is based around your monthly net income and outgoings, the current rate of interest being charged by the lender and a notional rate of interest which is supposed to reflect what might happen if mortgage rates increased over a fixed period.
The higher an applicant’s ‘discretionary spend’ (i.e. the amount left after your monthly expenses have been deducted from your take home pay) the better your affordability score. This is why revisiting your monthly budget and reducing fixed outgoings such as unused gym membership, magazine and netflix subscriptions and similar expenditure is well worth doing before you make your application.
Please contact our Bracknell office or speak to our preffered independent mortgage advisor, who will be happy to talk through your options.
Related articles:



 General news
 General news
 General news